
Most debt apps are built to make you feel behind
They colour your balance in alarm tones, count the days you’ve kept up, and offer two boxes: paid, or not paid. Real repayment isn’t like that. You pay a bit late. You pay half. You pay double one month because a payday landed well.
Mirian records what actually happened, and then gets out of your way.
Almost everyone finds this harder. Almost nobody says so.
of neurodivergent people say their neurodivergence makes debt harder to manage
didn't ask their creditors for help
of those who reach debt advice disclose being neurodivergent at all
The gap isn’t awareness. It’s shame — overwhelm, anxiety and stigma are the top reasons people go quiet at exactly the moment support would help most.
With a PDA profile it goes further. Demands themselves set off anxiety and avoidance, so the harder an app pushes “pay now”, the more surely it gets ignored. Mirian is built to lower the demand, not raise it.
Figures from StepChange and Equifax, 2025.
Enough detail to be honest, not enough to be a chore
Four honest states, not a tick box
Paid on time, late, part paid, or part paid and late. Each one has a word and a glyph, so you can read a year at a glance without decoding colours.
Overpayments are recorded too, and they move your date forward.
Late payments happen — what matters is you’re on it.
Notes on any payment
Why it was short, what you agreed on the phone, what to chase next month. Context without commentary.
Partial and overpayments
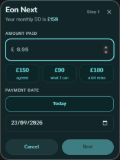
Pay £20 or pay double. Both get recorded properly, and overpayments pull your date closer.
Due dates per debt
Each debt keeps its own direct debit date, so you can see the month ahead without opening a bank app.
A debt-free date, front and centre
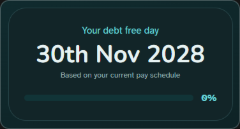
The one number that actually motivates: when this ends. It updates as you log.
Arrangements and contacts
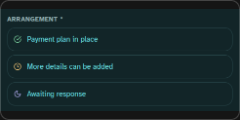
Plan in place, needs setting up, awaiting response — plus the creditor's number, kept with the debt.
Four steps, and you can stop after any of them
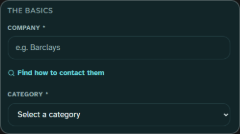
Add your debts
Company and amount is enough. The rest can wait, or stay blank forever.
Set up arrangements
Mark each one as in place, needs setting up, or awaiting response. Honest status, no pressure.
Log payments your way
On time, late, part paid, overpaid — with a note if you want one.
Watch the date come closer
Every payment you log moves your debt-free date. That's the whole reward.
Made for the brains that other finance apps quietly give up on
If instructions make you freeze, if the thought of opening a banking app makes your stomach drop, if you’ve abandoned three budgeting tools because they started nagging — that’s who this is for.
You don’t need a diagnosis to use it. You just need somewhere to write it down.
What people say
The way the app works gets rid of the drop in my stomach. Somehow it makes it far easier to use than other trackers I've tried.
Being able to log any payment I made and then put a note to remind myself what happened is really helpful.
Knowing EXACTLY when I'll be debt free is a game changer. I'm planning my party already!
Three things we’re working on
No dates attached — we’d rather show you than promise you. If the order looks wrong to you, say so and we’ll change it.
Your money and the bank's money, side by side
Your banking app shows one number. Some of that is yours and some is the overdraft. Mirian will show you both, separately, so a full-looking balance can't catch you out.
A nudge when it's time to chase
When you've sent a creditor a message and heard nothing back, Mirian will quietly remind you. No pressure, and no counting how long it's been.
A record you can hand over
Every payment and every message, as one file you can print or send. For the times someone asks you to prove it.
Questions people ask first
No judgment here. Let’s get it tracked.
Add one debt and see what happens. You can leave the rest blank, come back in a month, and nothing will have told you off.